New SMSF LRBA Rules: The Checklist for Practices and SMSF Advisers
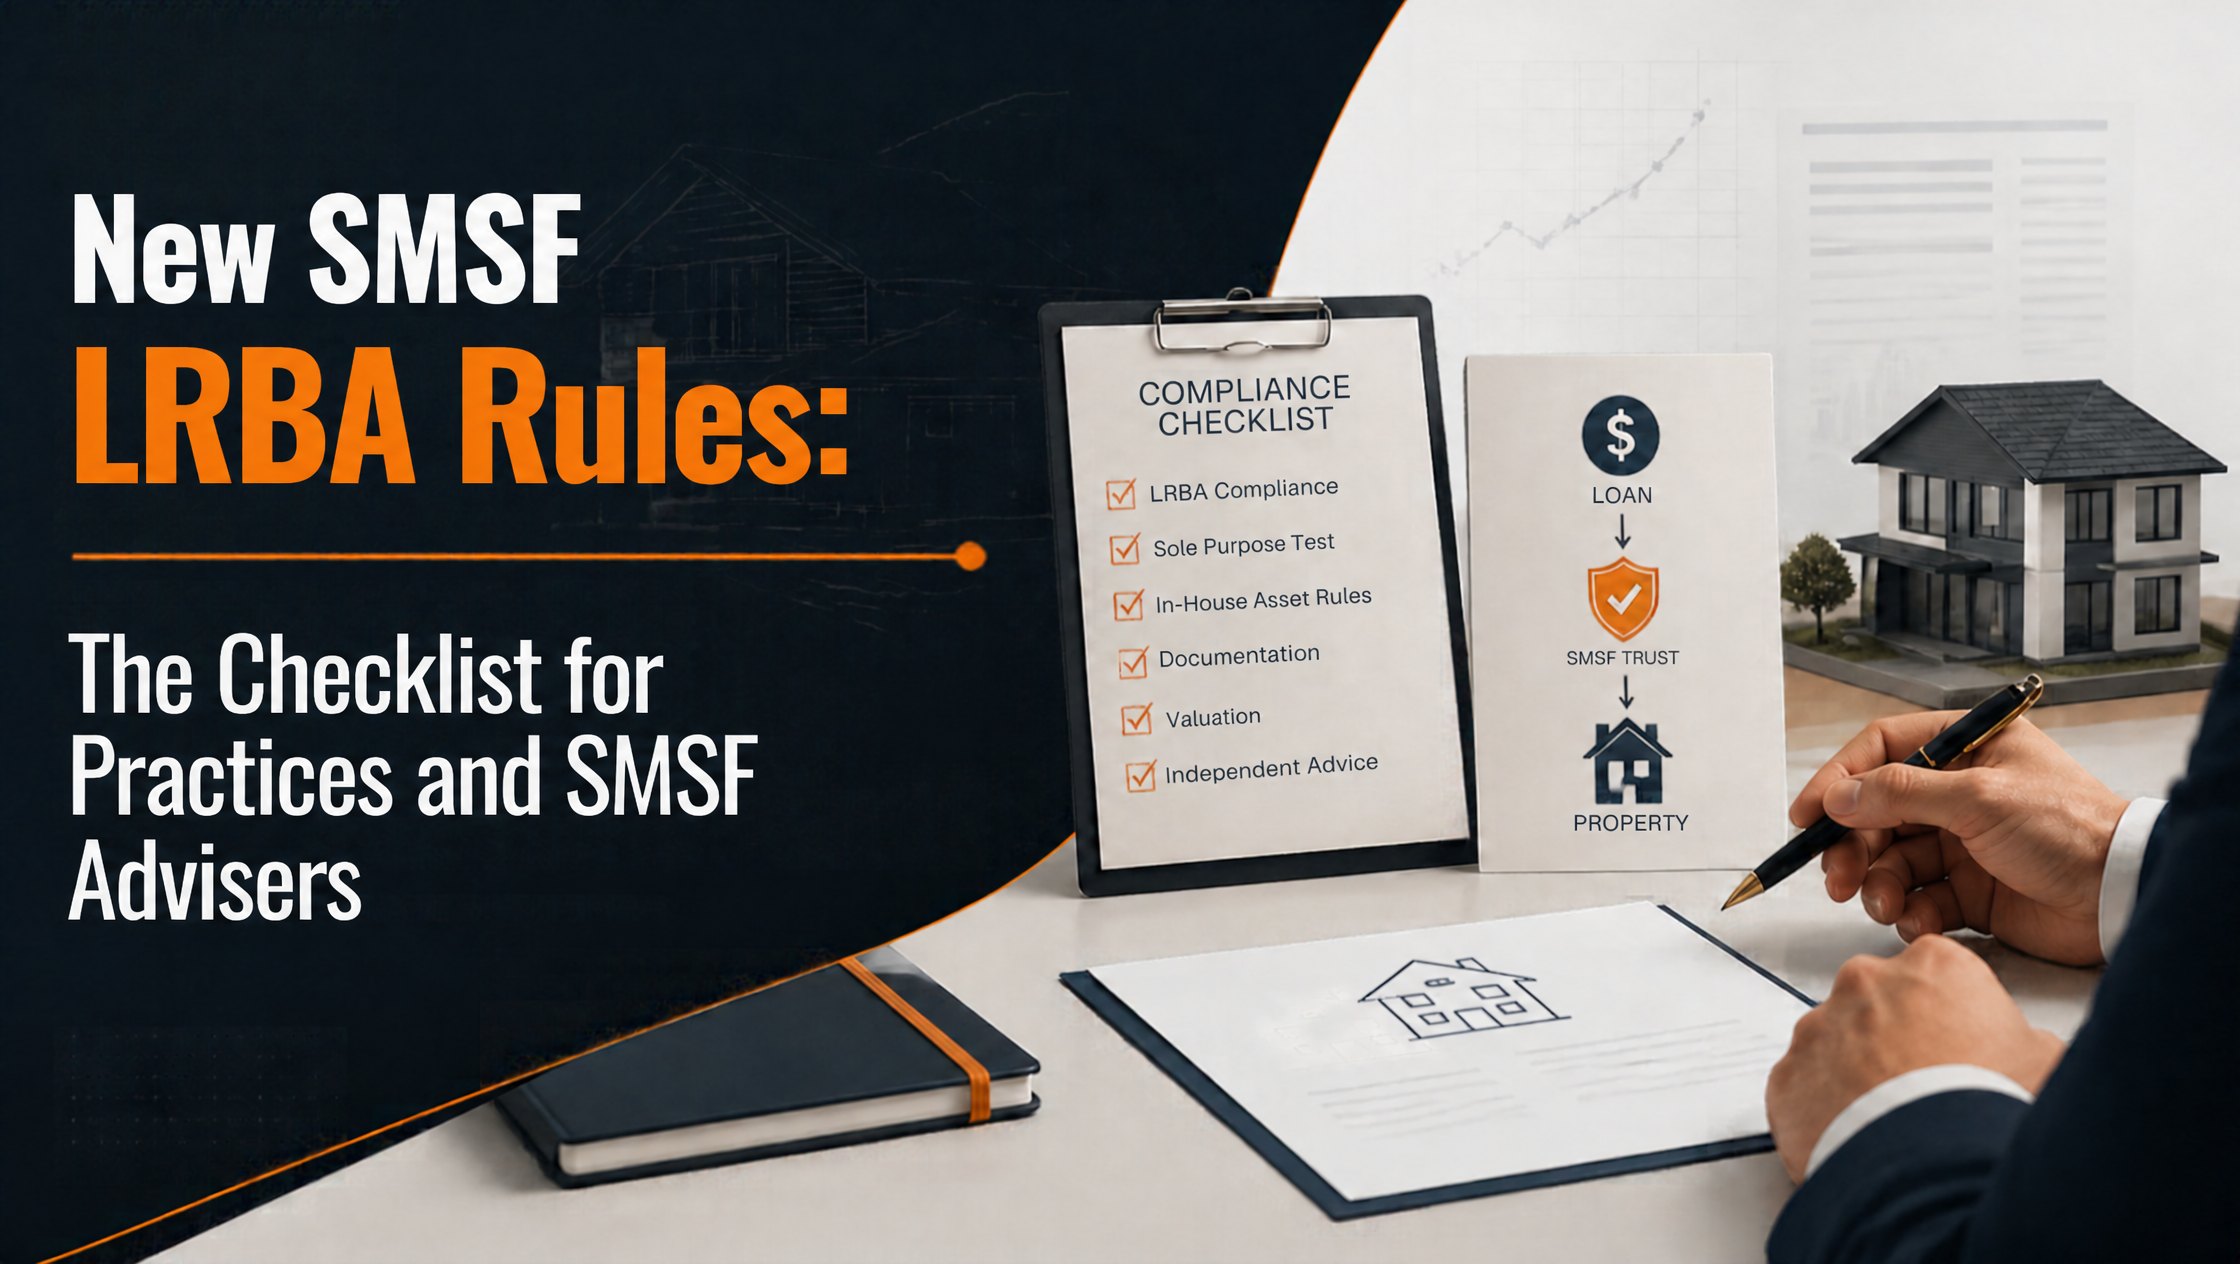
The SMSF LRBA rules changed for trustees. But most of the work will land on the practices and advisers who look after the fund.
The short answer. Any new limited recourse borrowing arrangement (LRBA) used to acquire real property must be over business real property, both when the LRBA is entered into and for the entire life of the arrangement. Existing LRBAs, and contracts exchanged before 10 August 2026, are unaffected. For the practice or adviser looking after the fund, that means two new routines: a check of every LRBA's contract and entry dates, and an annual business real property check with evidence the auditor will accept.
Most of the commentary on the SMSF LRBA changes has been written for trustees and lenders: can the fund still borrow, is the existing loan safe. But trustees are not the ones who will be asked for evidence at audit time. The practice that administers the fund, and the adviser who recommended the structure, will be.
This post is for Australian accounting practices and SMSF advisers, and for the outsourced accountant who does the processing on their behalf: what the law now says, how grandfathering and refinancing work under the ATO's guidance, and a checklist to run across your LRBA register before the first FY27 SMSF audit queries arrive.
If your practice is working out how to absorb this on top of the normal SMSF compliance cycle, a 15 minute call with us is the quickest way to talk it through.
1. What changed for SMSF borrowing
The change came through the Treasury Laws Amendment (Tax Reform No. 1) Act 2026, which received Royal Assent on 26 June 2026 and amended section 67A(2) of the Superannuation Industry (Supervision) Act 1993 so that real property acquired under an LRBA must be business real property as defined in section 66. The restriction applies to LRBAs entered into on or after 10 August 2026.
Four points matter for practices:
It is a restriction on the asset, not a ban on borrowing. In the ATO's words, SMSFs can still borrow or maintain a borrowing under an LRBA to acquire an asset. Where that asset is real property, it must be business real property.
The lender does not change the test. Bank, non bank or related party, the business real property requirement applies the same way. Related party loans still need to be on arm's length terms, and ATO's PCG 2016/5 provides safe harbour terms that can assist practices in assessing these arrangements.
Existing LRBAs are untouched. An LRBA entered into before 10 August 2026 continues, and can be maintained or refinanced on or after that date, without meeting the new test.
The fund can still hold residential property without an LRBA. The ATO's guidance confirms an SMSF can still hold non business residential property. What it cannot do is acquire that property through a new LRBA.
The ATO published its guidance on 28 July 2026 and updated it on 26 October 2026. Draft updates to SMSFR 2012/1 (LRBA key concepts) and SMSFR 2009/1 (business real property) followed in October, with comments closing on 27 November 2026 (section 5).
2. The business real property test, at entry and for the life of the loan
Business real property, as defined in section 66 of the SIS Act, is real property used wholly and exclusively in one or more businesses, whether or not the business is carried on by the fund. Peter Burgess of the SMSF Association summarised the practical effect when the Act passed: a property zoned residential and used in a business could meet the definition, while a commercial property only partly used in a business would not.
For an LRBA entered into on or after 10 August 2026, the ATO's guidance applies that test at two points:
At entry. If the property is not business real property when the LRBA is entered into, the SMSF has breached the borrowing prohibition in section 67 of the SIS Act, and compliance action may apply.
For the entire life of the LRBA. The ATO's words are that the real property must remain business real property for the entire life of the LRBA. If it stops qualifying while the borrowing is in place, the arrangement is no longer being maintained as an LRBA, and compliance action may follow.
Three further points in the ATO's guidance, as updated on 26 October 2026, set the boundaries:
Intention is not enough at entry. Where use of the premises in a business is delayed, for example while approvals are awaited, the ATO's position is that the SMSF needs to show the business has commenced at the time the LRBA is entered into.
A vacancy is not automatically a failure. A property between tenants, where the owner is actively seeking a new business tenant, remains business real property. A property where the owner has given up plans to lease it to a business, or has moved it to another use, stops being business real property from that point.
Resuming business use does not cure the gap. If business use stops and later resumes, the property is business real property again from that point, but the ATO states that this does not remove the original borrowing breach.
The whole of life limb is the one that changes SMSF administration. At the SMSF Association Technical Summit in July, Shelley Banton of Super Clarity said trustees may need a document recording their intention for the property over the period of the LRBA, which can be 20 years or more, and that auditors may have to change their procedures to obtain evidence from the property itself. Somebody has to confirm, every year, that the use has not changed, and keep the evidence.
3. Grandfathering and refinancing: the date that matters is exchange
The ATO's guidance sets out how existing arrangements are treated. These are the rules to record on each file:
Contract exchanged before 10 August 2026. Where the fund exchanged a binding contract to acquire the property before 10 August 2026, the LRBA is unaffected even where settlement and the loan itself happen afterwards. The exchange date is what matters, not settlement.
Conditions precedent. The contract must not be subject to a condition precedent to the formation of a legally binding contract. DBA Lawyers' advice is not to assume that a contract subject to finance involves a condition precedent, and that the analysis is best done by a lawyer.
Off the plan. An off the plan contract exchanged before 10 August 2026 is protected even if finance is approved or settlement occurs after commencement. DBA Lawyers flags one risk: a replacement contract issued after a rescission may fall after that date.
Variations. Later variations to a grandfathered contract generally do not create a new arrangement, unless the change is so substantial that the fundamental terms no longer exist.
Refinancing. The ATO treats refinancing as entering into a new loan contract for the same asset. A refinance of a pre 10 August LRBA over the same property does not bring it under the new rules; changing the asset starts a new arrangement.
For the practice, the consequence is simple: every LRBA file needs the contract exchange date, the LRBA entry date and the settlement date recorded separately, with the contract on file. Those three dates decide which regime the borrowing sits in.
4. The practice checklist for SMSF LRBAs
Run this across every fund with a borrowing, whether the processing sits with the SMSF accountant in the practice or with an outsourced accounting team.
For every LRBA on the register
Record the three dates. Contract exchange date, LRBA entry date and settlement date, with the contract, loan agreement and holding trust (bare trust) deed on file. Flag any arrangement where exchange was on or after 10 August 2026.
Classify the arrangement. LRBA entered into before 10 August 2026, contract exchanged before 10 August 2026, or post 10 August with business real property required. Add the classification as a field in BGL Simple Fund 360 or Class so it carries forward each year.
Check the refinance history. For any refinance since 10 August, confirm it is a new loan contract for the same asset.
Check contract variations. For grandfathered contracts varied after exchange, keep the variation deed and a note on why the fundamental terms are unchanged.
Confirm the holding trust and title. Legal title in the holding trustee, beneficial interest in the fund, recourse limited to that asset, and arm's length loan terms where the lender is a related party.
For every post 10 August LRBA, at entry
Evidence that a business was operating at the date of entry. The ATO's position is that the SMSF needs to show the business had commenced when the LRBA was entered into. Keep the lease, the tenant's ABN, evidence that the business is trading, and outgoings from the entry date.
Whole of property test. Confirm the property is used wholly and exclusively in one or more businesses, taking account of any relevant statutory exceptions.
Trustee intention document. The document Shelley Banton suggested: a minute recording that the property is held for use in a business over the period of the LRBA, signed at acquisition.
Every year, for every post 10 August LRBA
Occupancy and use review. Who occupied the property during the year, under what lease, for what use. Any period of vacancy logged with the steps taken to lease it to a business again.
Change of use check. Any change in how the property is used, or any period in which no business is carried on from it, is raised with the trustee and the auditor before year end, not after.
Audit workpaper. A one page LRBA summary per fund: classification, dates, business real property evidence, vacancy log, loan balance and repayments.
Client letter. A short annual note to trustees with post 10 August borrowings reminding them that a change in the property's use affects the borrowing, and asking them to tell the practice before they act.
Most of this is record keeping rather than advice, which is why it sits naturally with whoever already runs the fund's processing, whether that is the SMSF accountant in the practice or an outsourced accounting team. If the fund is processed by an outsourced accountant or an offshore accounting team, the LRBA register and the annual evidence pack should be written into their scope rather than assumed. How we structure that is on our SMSF administration page.
5. What the ATO has not settled yet
The ATO's draft updates to SMSFR 2012/1 and SMSFR 2009/1, released in October 2026 together with minor updates to four related guidance products, are open for comment until 27 November 2026. Two positions from the profession are on the record:
The SMSF Association said the ATO had moved quickly to provide guidance, and asked for further guidance on the types of post exchange contract variations that could be treated as a new arrangement, and for the review of SMSFR 2009/1 to bring greater certainty on how the business real property rules apply in practice.
The Auditors Institute and the Institute of Financial Professionals Australia asked the Senate Economics Committee to exempt new residential dwellings from the restriction, using the definition of a new residential dwelling in the Income Tax Assessment Act 1997.
None of this changes what applies now. The law has applied since 10 August 2026, and the evidence the auditor needs has to exist from the acquisition date. Build the register and the evidence files now; adjust the detail when the rulings are finalised.
6. What this means for SMSF administration capacity
Add this to what is already on the FY27 calendar: the 2026 SMSF annual return's auditor fee labels (H1 and H2) becoming mandatory and its clarified modified opinion instructions, Payday Super reconciliations, and an SMSF auditor population the ATO put at 3,760 and falling. Every LRBA on the books now carries a permanent annual review and evidence task on top.
That is process work, and it is the kind of work practices increasingly move to outsourced accounting services, and for funds specifically to SMSF outsourcing: maintaining the LRBA register, collecting the business real property evidence, preparing the audit workpapers and chasing the trustee minutes, while the practice keeps the advice, the review and the sign off. The same logic we set out in Local or Outsourced? It's Not Just About Cost Anymore applies here: the question is not the hourly rate, it is whether the file is complete when the auditor opens it.
At Venus Accountants our SMSF outsourcing services cover exactly this layer for Australian accounting practices and SMSF advisers: SMSF administration services, SMSF accounting outsourcing and audit support in BGL Simple Fund 360 and Class Super, with a manager reviewing the super funds.